Mirador Portfolio Management Update for the Third Quarter of 2026
By Stan Clarke, October 26, 2026
Gratitude, Uncertainty, and Staying Defensive
Dear Friends and Clients,
I hope you have been enjoying the lovely autumn colors. Recently, it was –9°C here in the southwest hills, and I always feel for the newborn animals on the first chilly day of the season. We also had two snowfalls of more than six centimeters each over the Thanksgiving weekend. Speaking of Thanksgiving, I hope you all enjoyed a wonderful feast. I am especially thankful for my family and for you, our clients.
I apologize that this note is arriving later - and it being somewhat longer than usual. Geopolitical developments and other factors discussed below have made the portfolio management more time-consuming, and several projects have reduced my time available for writing. Given the number and significance of the issues affecting the markets currently, I believe a more detailed update is warranted.
Before getting into the update, I want to speak directly to the new clients who recently joined Mirador. Thank you for placing your trust in us. We know this is a significant decision, and we will do our very best to make it the best and last major investment-management decision you need to make. I also want to thank the clients who referred you to us. They put their reputations on the line, and we value and respect that greatly.
Last quarter, I began with a discussion of seasonality and the saying “sell in May and stay away.” So far, it has proved a reasonably useful heuristic - the behavioral finance term for a “rule of thumb.” Although there has not been a major decline, it has been a difficult and mostly unfruitful period for investors, especially for income investors like those in the MISF, with frequent swings but few sustained, investable trends. Roughly six weeks remain in this historically unfavorable season, and our positioning is close to the most defensive it has been in quite some time. To satisfy your interest in the stories behind the market’s weakness, I will outline the principal factors shortly. Remember, however, that stories do not drive Mirador’s actions. Our portfolio-management decisions are driven by data and evidence.
As you know, after 36 years in this business, I have developed an extensive collection of investment observations, quotations, and lessons drawn from experience and wide-ranging reading. One recurring truth is that when conditions deteriorate in the capital markets, correlations tend to move toward one. For readers who are less statistically inclined, a correlation of one means that two or more assets move together in tandem. We have seen signs of that lately: stocks have been under pressure, bond prices have fallen, the Canadian dollar has weakened, and precious metals have declined. Increasingly, assets that normally behave differently are moving in the same direction.
You have also heard me describe the stock market as a leading indicator of the economy. Within the market, certain sectors have historically provided particularly useful signals of an economic slowdown. Once again, this is about following the money. Imagine that you manage a fund worth hundreds of billions—or, these days, perhaps a trillion dollars—and your mandate requires you to remain invested in stocks. If equities begin to perform poorly, you cannot simply sell everything and move to another asset class.
Instead, you position the portfolio in sectors that have historically declined less during difficult periods and avoid those that tend to be hit hardest. The more resilient areas are known as defensive sectors, including consumer staples and health care. Recently, we have seen relative strength in these areas. Conversely, economically sensitive sectors such as transportation and technology often weaken earlier and decline more sharply. The transportation sector and parts of technology, including semiconductors, have been falling for some time. Some are now in correction territory and approaching bear-market territory.
Markets do not like uncertainty, but uncertainty is always present. I sometimes laugh when I see an advertisement or social-media post promising to explain how to invest in uncertain times. If uncertainty did not exist, making money would be easy and our profession would scarcely be necessary.
The stories surrounding markets are a major source of that uncertainty, and today there is no shortage of negative narratives. Most of you follow these developments, so I will simply list the principal stories without offering a lengthy dissertation on how each might affect the future:
- The Russia–Ukraine conflict and its implications for global commodity prices and European geopolitical and economic stability.
- Conflict involving Iran, with implications for global security, energy and other commodity prices, and countries throughout the Middle East, as well as the United States and China.
- Dramatic developments in the bond market. Volatility and rising yields at both the short and long ends of the curve have been significant. Higher oil prices are adding to inflationary pressure, while potential efficiencies from AI may exert a cooling influence. Central banks face the difficult task of containing inflation without causing undue harm to employment. There is more written about the effects of rising bond yields on the MISF further below.
- Political uncertainty in Canada and the United States.
- Alberta’s October 19 referendum asks voters to consider ten questions involving immigration, social programs, election rules, constitutional reform, and whether the province should remain in Canada or begin the legal process toward a future binding separation vote. The breadth and sensitivity of these issues could affect business confidence, intergovernmental relations, the Canadian dollar, and investment decisions.
- In the United States, the November 3 midterm elections will determine control of the House of Representatives and a significant portion of the Senate. The result could materially influence fiscal, trade, regulatory, and energy policy, as well as the administration’s ability to advance its agenda. This may create additional market uncertainty before and after the vote.
- The Trump Tariff Tantrums continue
- Artificial Intelligence (AI) and the scale, speed, and financing of its development.
Regarding Artificial Intelligence, I have lived through many major market declines. Looking back, the dominant news story preceding a decline is often not its underlying cause. Today, mainstream discussion about AI focuses largely on potential productivity gains and effects on labor markets. Other risks, however, deserve closer attention. I see three broad possibilities:
- A major operational or societal disruption involving inadequately controlled AI systems.
- The rapid growth of AI-generated content. I am concerned about its use in deception and the possibility that it could erode confidence in online information, reduce trust in social media, and create significant new legal and compliance costs.
- The scale and financing of the capital expenditures required for AI expansion, including data centers, power infrastructure, semiconductors, processors, and cooling systems. From a risk-management perspective, I am concerned that excessive leverage, opaque financing structures, or unrealistic growth assumptions could create financial stress. Some current financing practices warrant careful scrutiny, particularly where they resemble vulnerabilities exposed during the 2008–2009 financial crisis.
I am not making predictions. I simply want you to know that these AI risks are on our radar and remain central to our research, portfolio construction, and risk-management decisions. They may be more important than the wars and tariffs dominating the news. Joyce and I are using AI more frequently, and we believe it can be a valuable tool when used responsibly. We do not view it simply as a threat; rather, we believe individuals and organizations that fail to understand and adopt it thoughtfully may be placed at a competitive disadvantage.
Additional words regarding the Bond Market; Bond yields go up as a result of their prices going down. The downward movement of bond prices is contagious - other securities like dividend stocks and preferred shares are also under pressure due to the bond market weakness. This makes it more challenging to manage for high income with stability and capital preservation. The MISF programs are designed to make the best out of troubling situations like this, but it is not easy, and our results are not expected to be as good as they were in the last few years.
Given the concerns outlined above, together with deterioration in the data and our models, we are positioned more defensively today. The potential downside warrants greater caution than usual. It is better to miss an opportunity than to lose capital. At present, the balance of risks suggests a heightened possibility of loss, so we maintain elevated cash levels and broad-market short positions. We will continue to monitor the evidence and adjust portfolios as conditions change.
At this time, we are forecasting that there will be a bonus distribution at year-end. Based on our current estimates, units held on January 1, 2026, would receive total annual distributions in the 9% range. We are hopeful that greater stability during the remainder of the year will allow us to provide this planned bonus distribution and preserve or increase the modest YTD increase in unit value. Together, these outcomes would represent an attractive total return for a low volatility income program. And, the after-tax cashflow yield of the MISF program is the best we know of.
In the Wealth Planning Department…
Now that we are in the final quarter of the year, Joyce will be forecasting client’s 2026 income and working with many of your tax advisors to determine if there are any planning opportunities to be implemented prior to year end. Joyce will also be working closely with me to analyze and plan the Mirador Income and Stability’s (MISF’s) bonus distribution for 2026 as well as the 2027 distribution declaration.
On the Personal Side…
Joyce took full advantage of the beautiful fall season, enjoying several hikes in the Kananaskis area as well as kayaking on the lower lake. It is her favorite season, and this year was particularly glorious with the many fall colors.
Emily is now well into her first year of university at U of C and is just wrapping up her season with the U of C women’s rugby team. She is doing very well in her classes and enjoying being part of a varsity sports team, although she is currently recovering from several injuries.
Jessica continues to recover from her knee injury which has proven to be more challenging than originally anticipated. She is now preparing for surgery early in the new year.
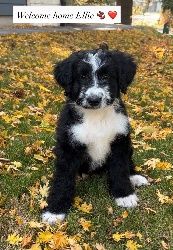
And most exciting, we have a new addition to our family! On Saturday the girls picked up an 8-week-old Bernedoodle – Ellie is a bundle of joy (and energy) so there is never a dull moment it seems.
That’s it for Q3 2026. You will have your Mirador portfolio reports and the MISF quantitative review on Wednesday. As always, phone or reply to this email to just say hello, or if you have any questions comments or ideas.
Sincerely,
Stan 403-608-4664
Joyce 403-978-6798